

Changes Over the Last Three Years
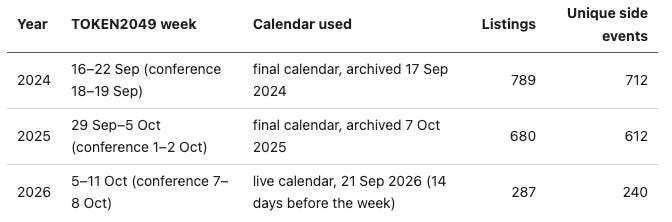
The number of side events has dropped significantly. This year we have 57% fewer side events than last year, and last year already had fewer than the year before. We went from 789 to 680 to 287 this year.
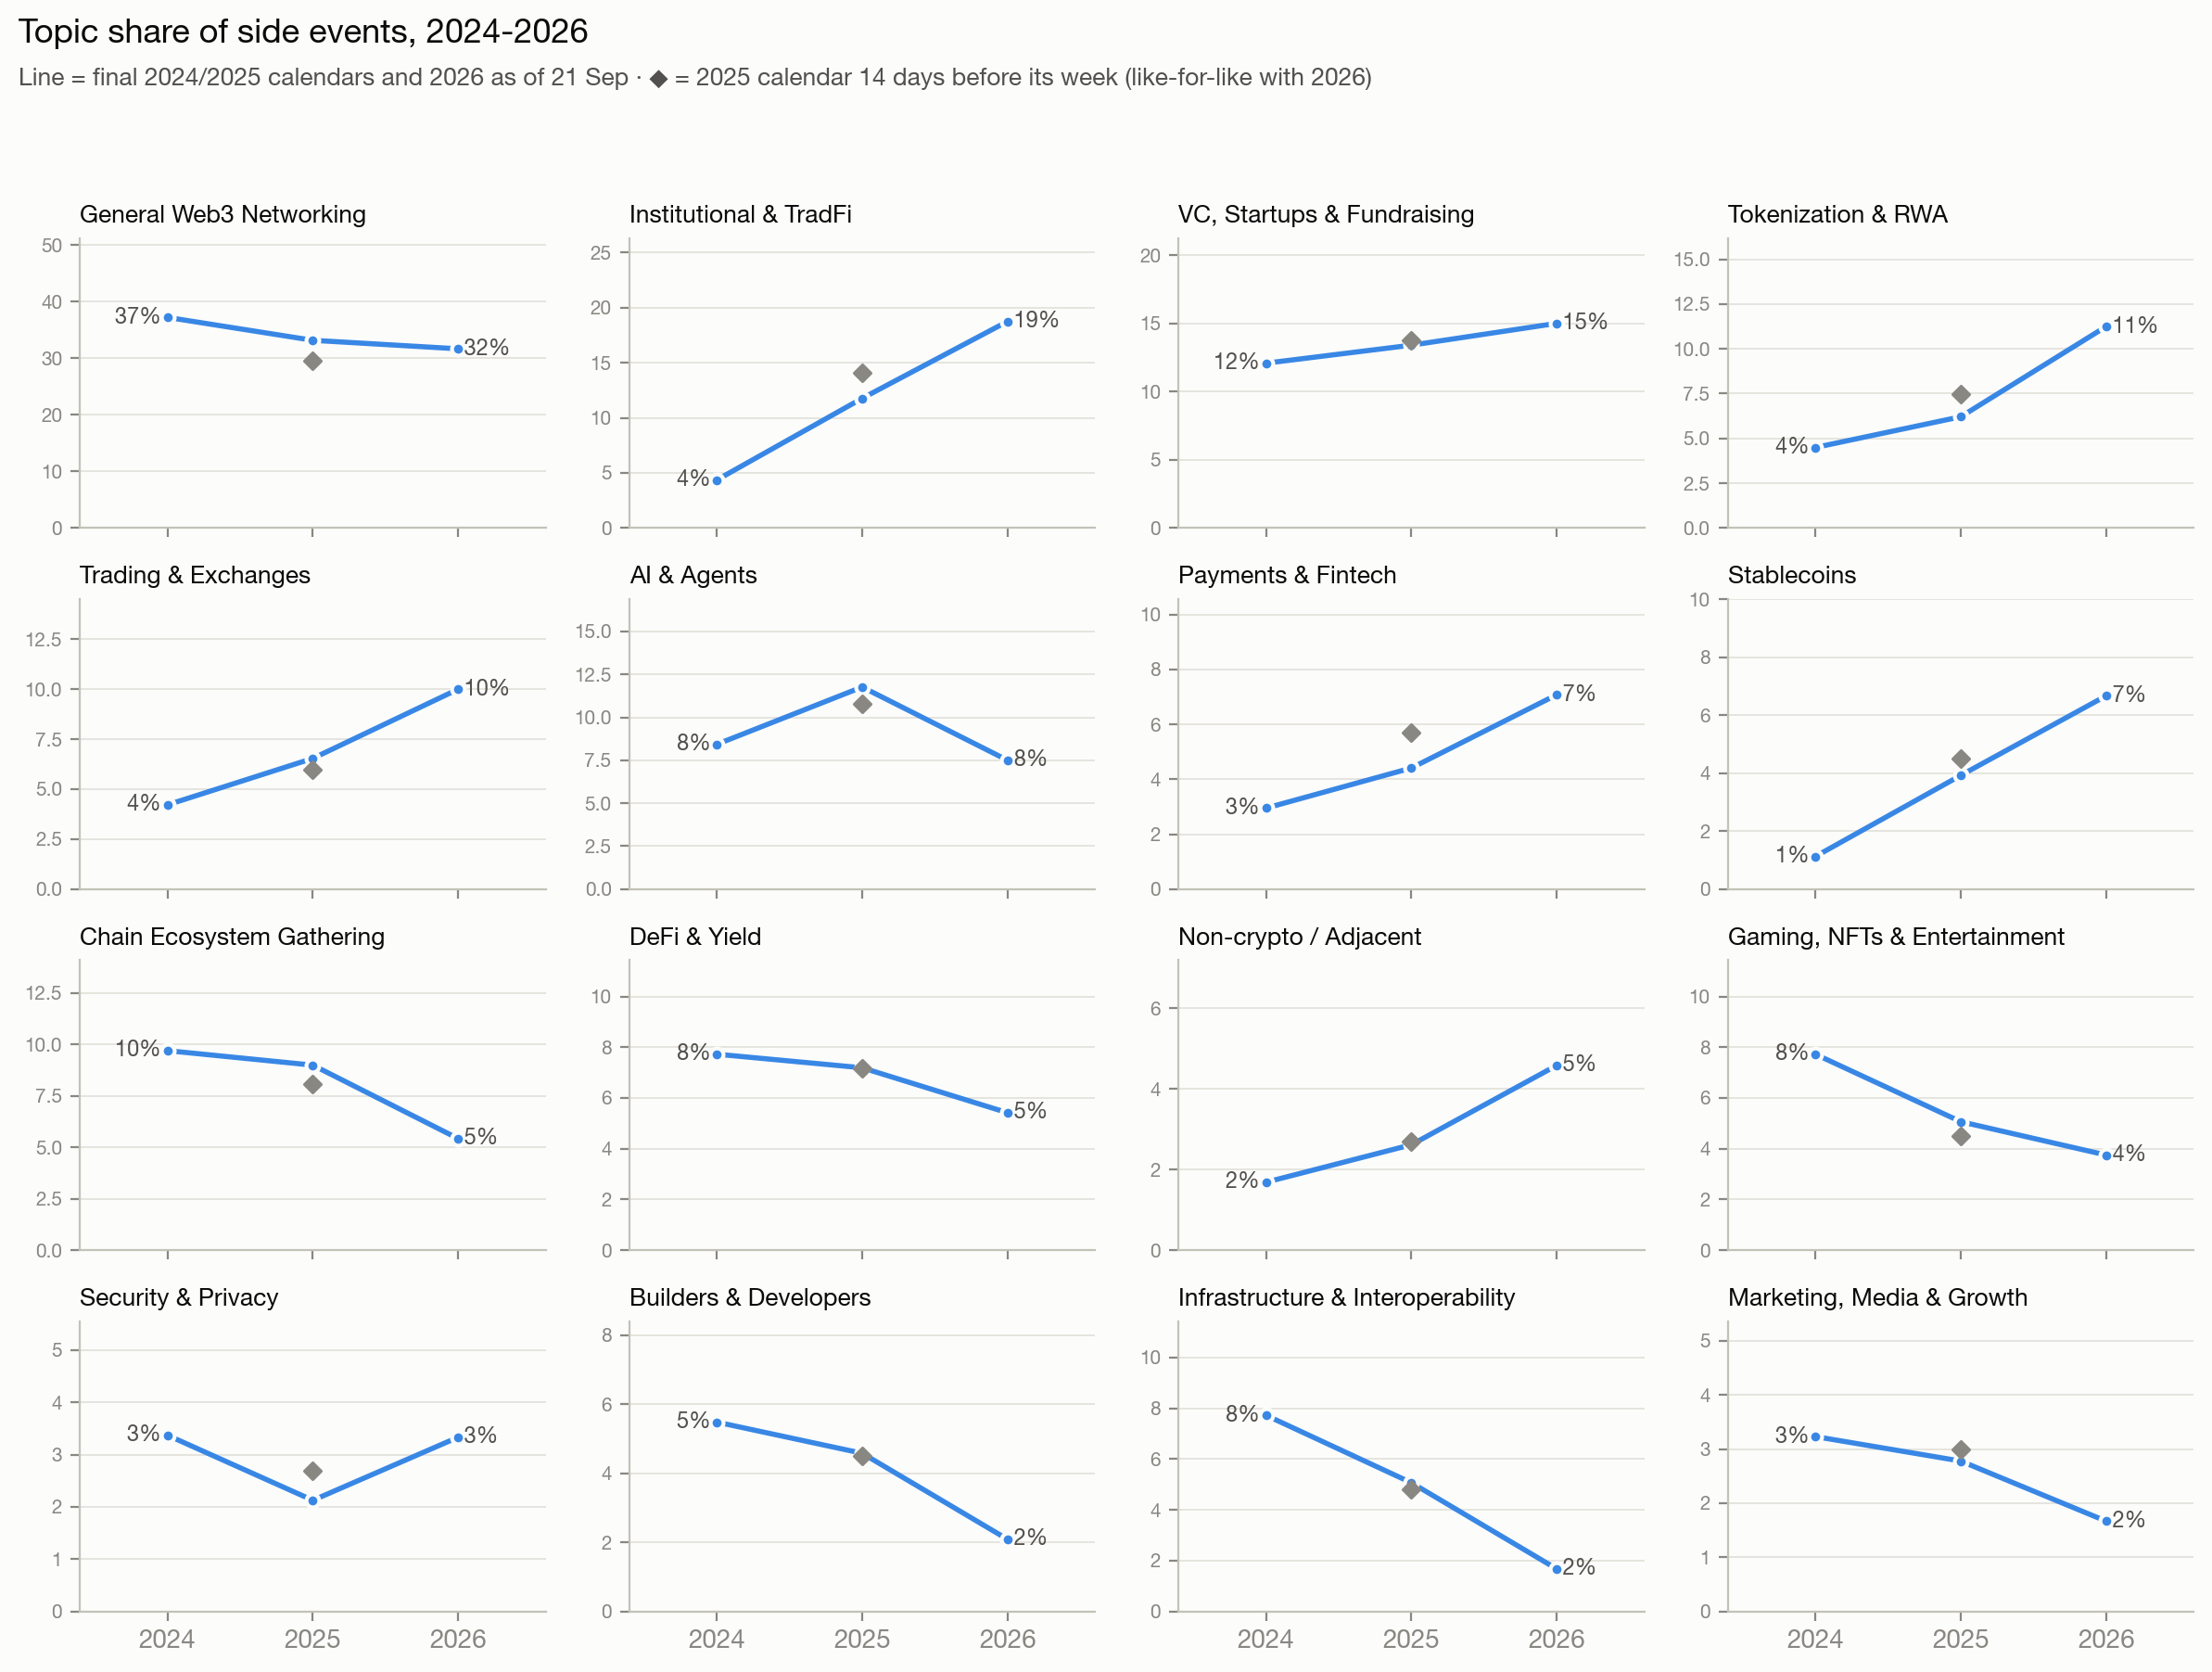
The money and markets bucket moved from capturing only 21% of all events in 2024 to 31% in 2025 and 43% this year. The institutional and TradFi bucket alone moved from 4% to 12% to 19% this year. All sections jumped significantly: stablecoins jumped from 1.1% to 6.7% of events, tokenization/RWA from 4.5% to 11.2%, trading and exchanges from 4.2% to 10%, and payments from 2.9% to 7.1%. These now represent the new market.
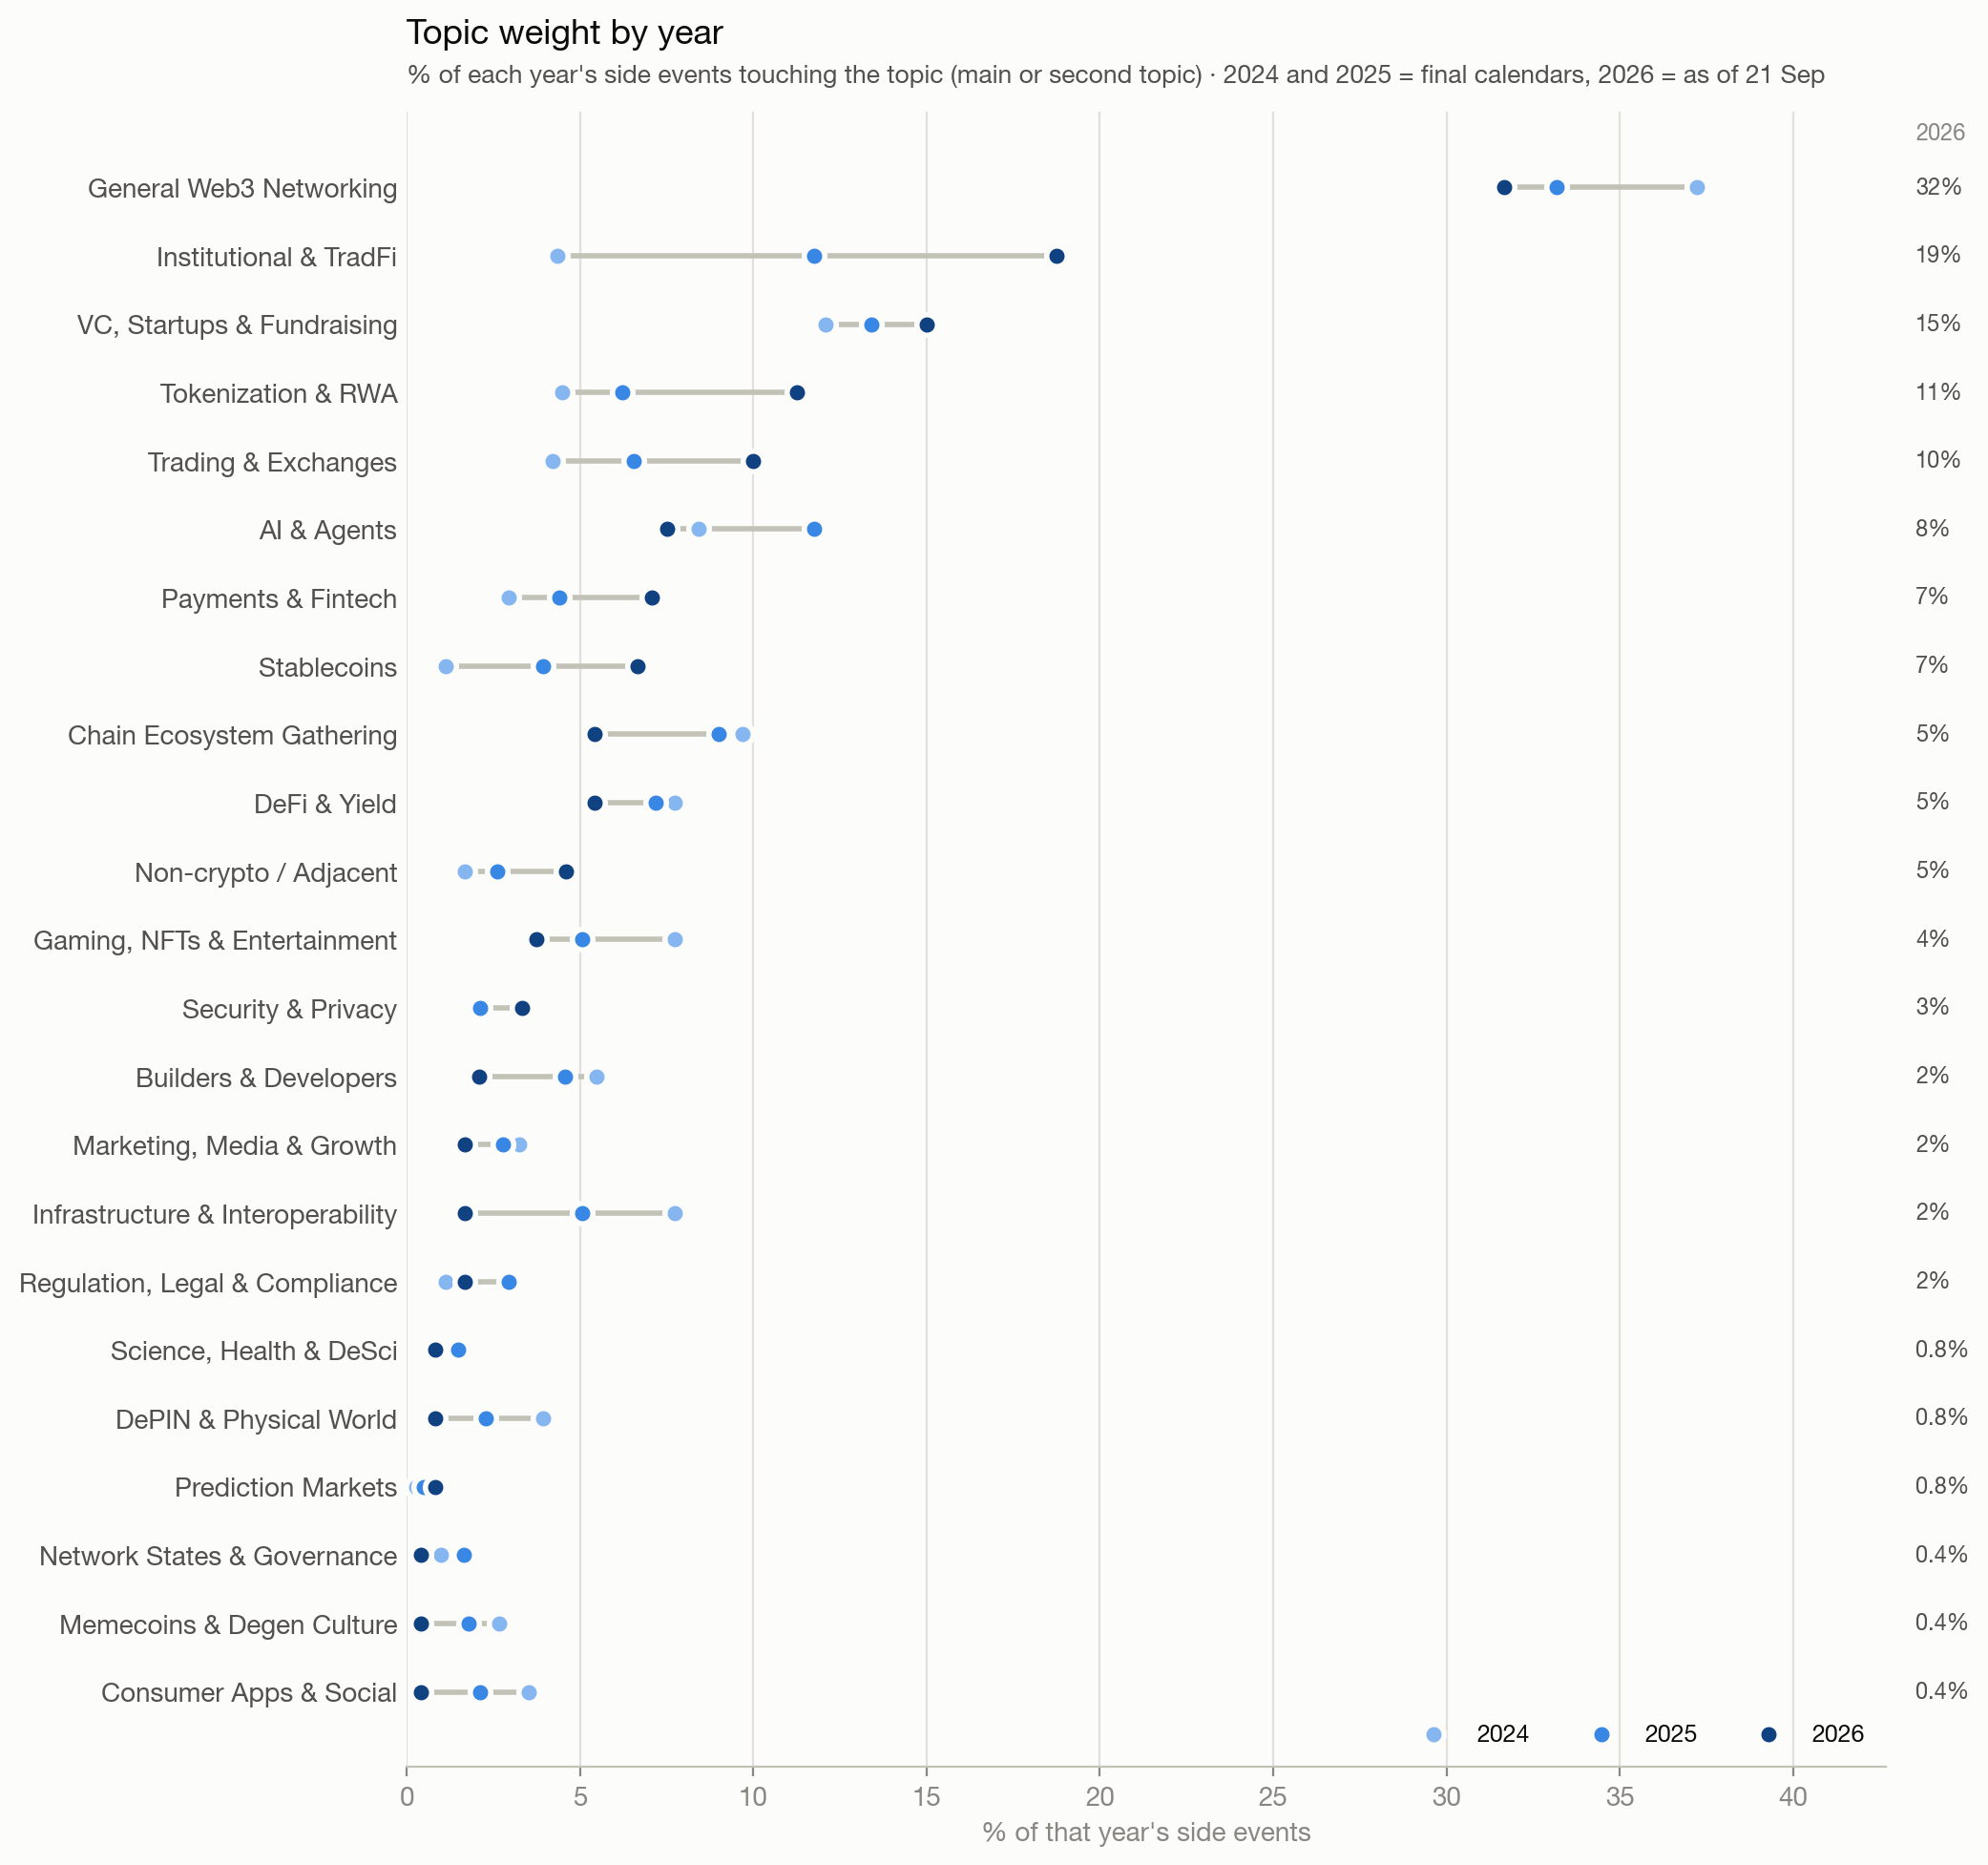
Meanwhile, crypto-native tech and culture lost weight: infrastructure fell from 7.7% to just 1.7% this year. Chain ecosystem gatherings fell from 9.7% to 5.4%, builders/devs from 5.5% to 2.1%, gaming/NFTs from 7.7% to 3.8%, DePIN from 3.9% to 0.8%, consumer apps from 3.5% to 0.4%, and memecoins from 2.7% to 0.4%. This is a big market change, and it shows where the eyes are.
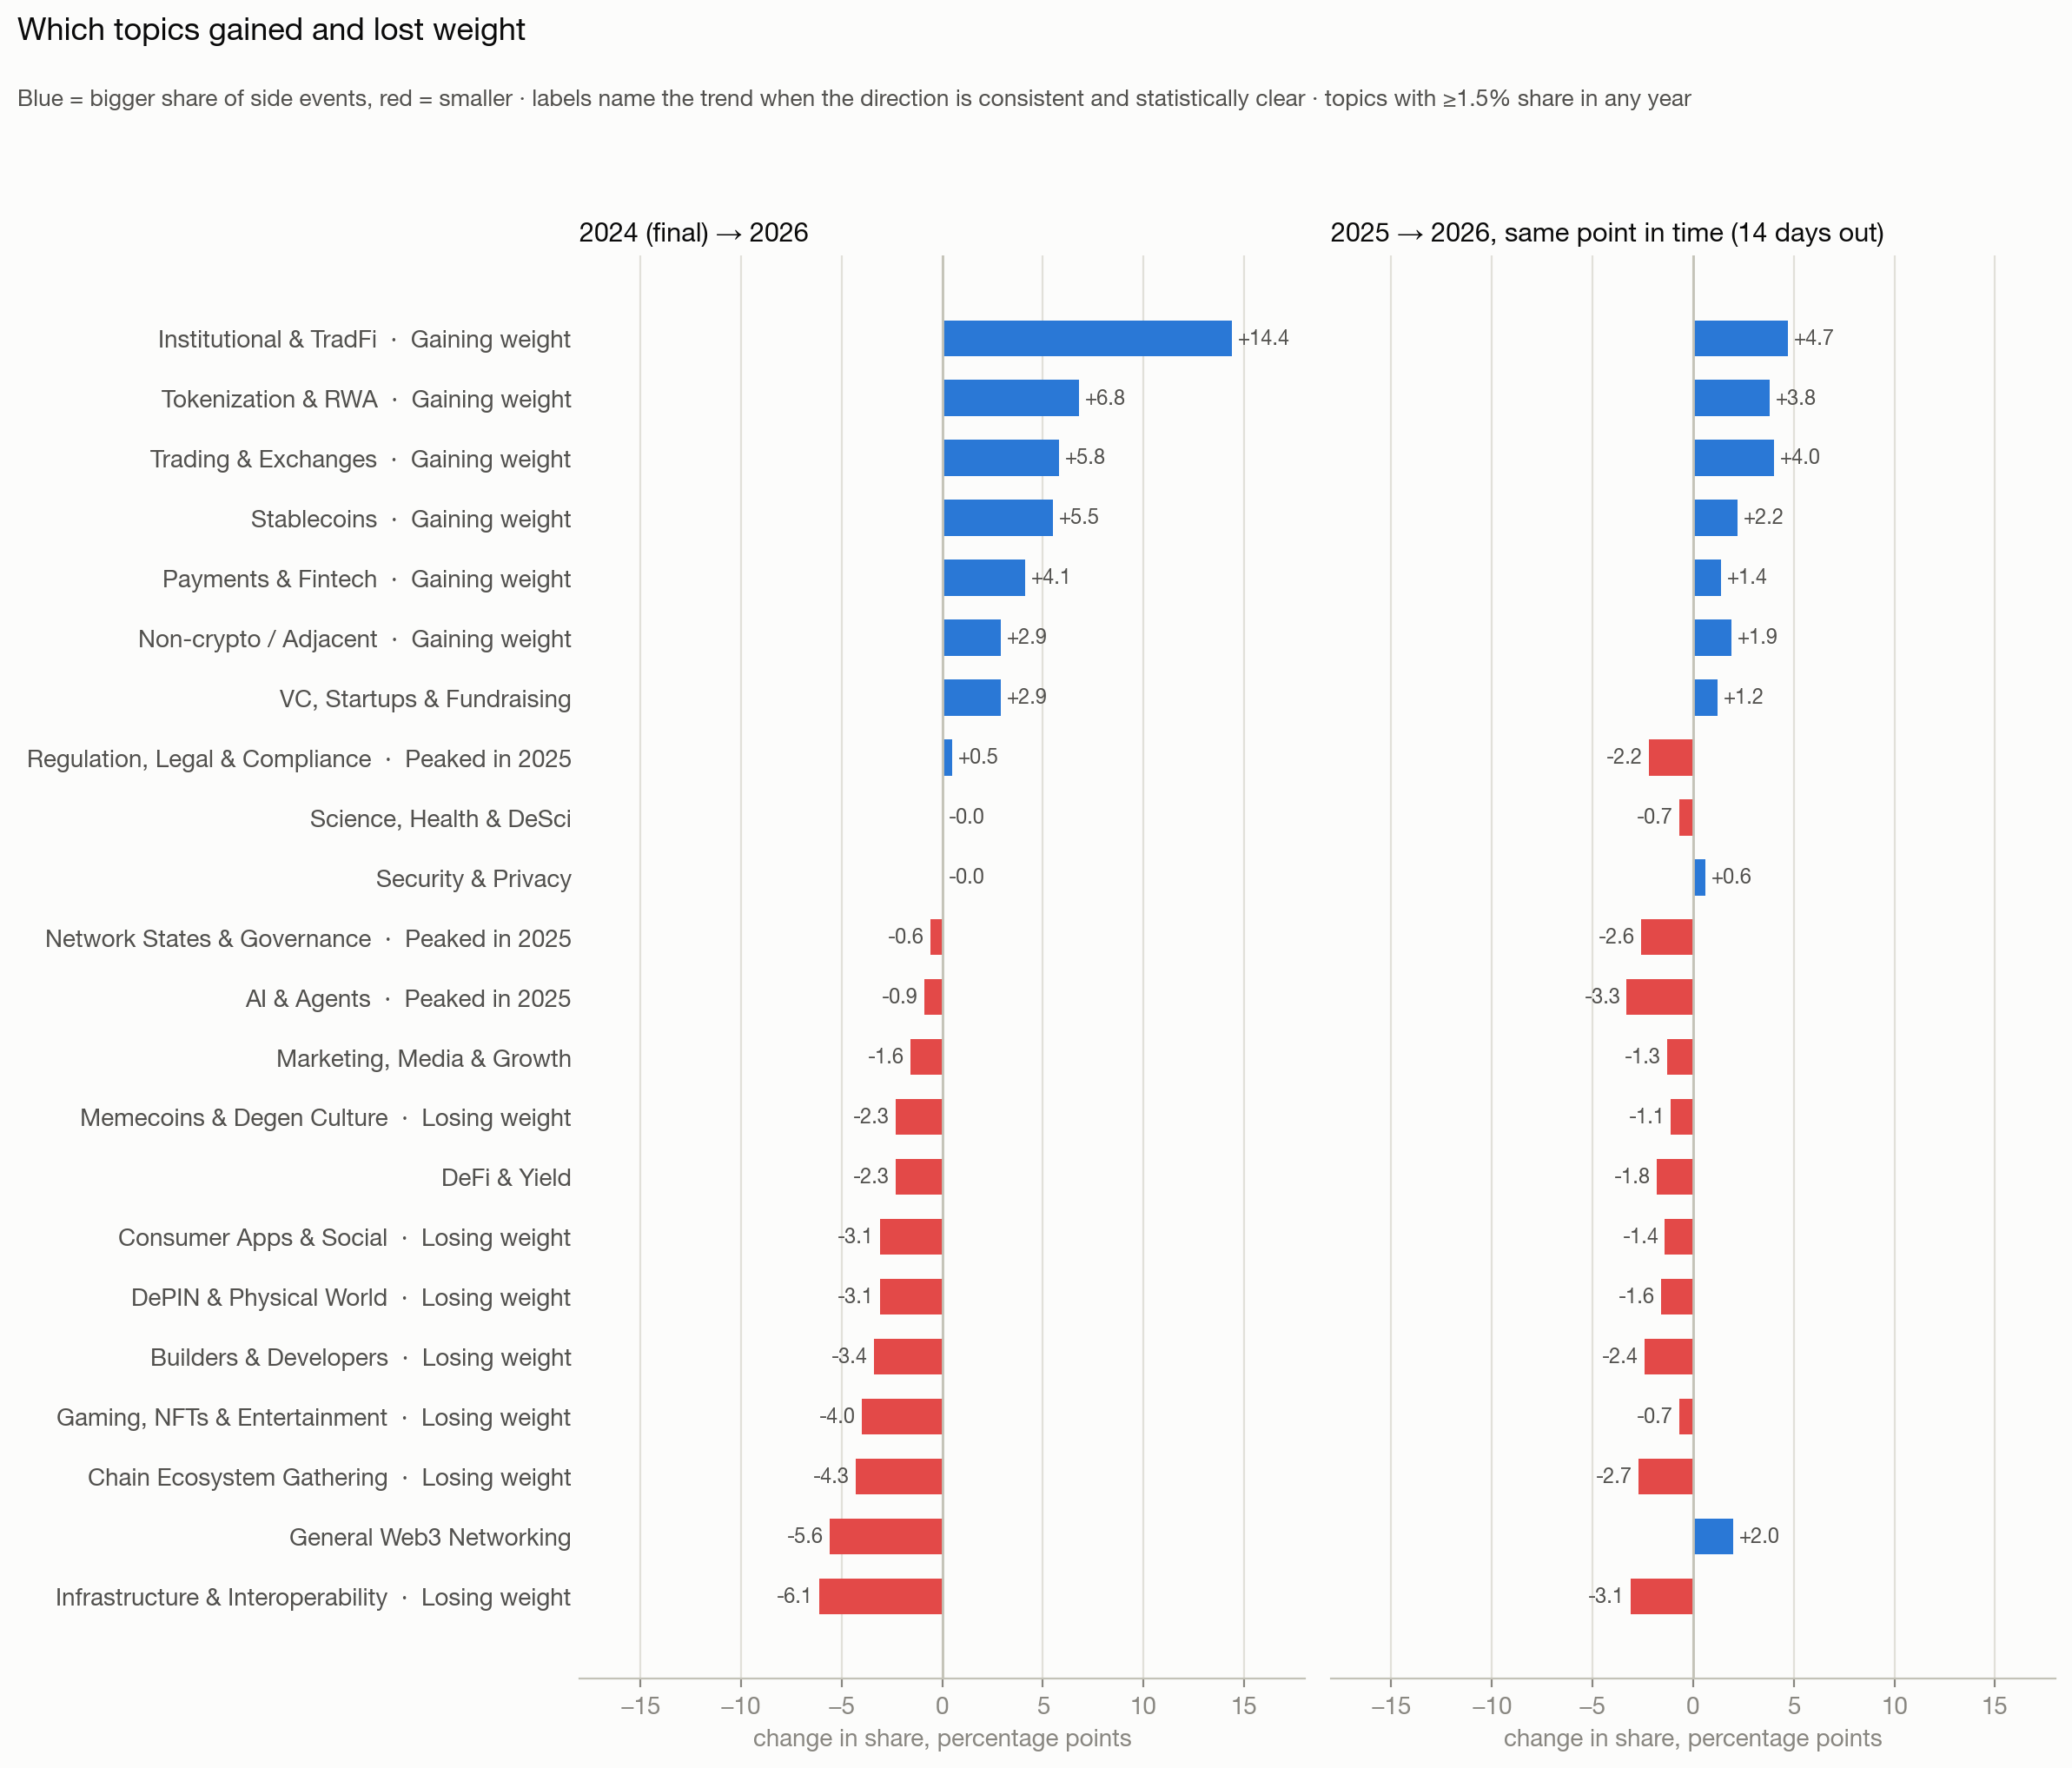
AI event penetration peaked last year at 11.8% of all events, then came back down to just 7.5% this year, below the 2024 level.
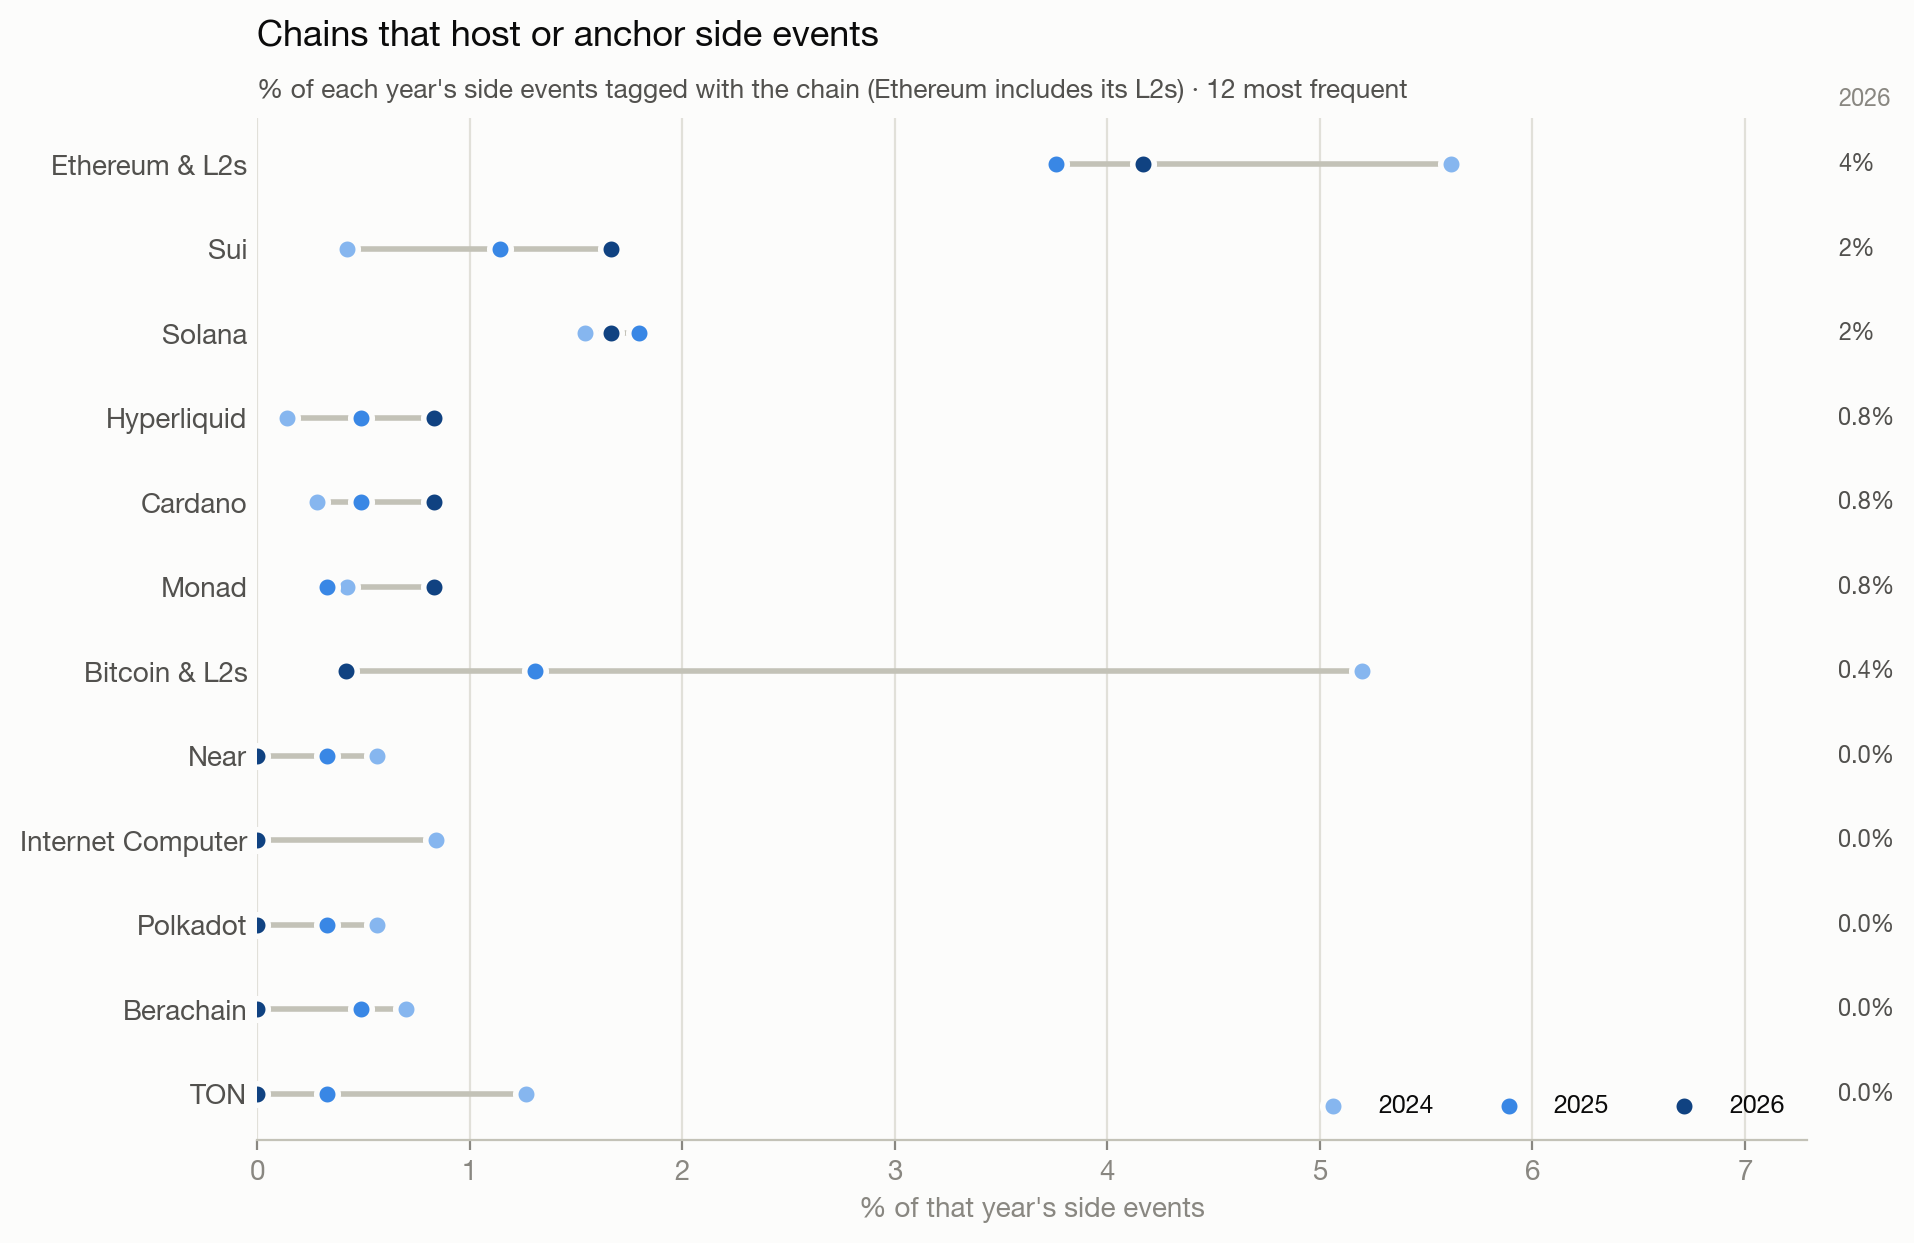
A key metric is that there are very few events built around chains. What used to be a big event marketing campaign is no longer a real thing. Chains are not generating events: TON, for example, used to have 9 events and this year has zero. Bitcoin, its L2s and ordinals collapsed from 37 events in 2024 to just 1 this year.
Another key insight is that events are shifting from party-driven to exclusive. There are a lot of events in the invite-only category, which grew from 16% to 27%, while parties fell from 17% to 9% of events. Flying to TOKEN2049 week to party is not relevant; the industry is maturing.
The direction from 2024 to 2025 is the same from 2025 to 2026. No doubt about it.
The 2026 Week in Detail
This year, side events are all about institutional and TradFi. This is where the largest share of events ends up: 19%, or 45 events. VC, startups and fundraising follow, obviously, with 15%, then tokenization and RWA, and trading and exchanges, with 11% and 10% respectively. AI and agents account for only 7.5% (18 events); I expected this number to be higher. Payments and fintech account for 7% (17 events). Stablecoins and DeFi are very small, at 6.7% and 5.4% respectively. There is only one side event in the memecoins and degen culture bucket. Even though all the activity is in memecoins, there is no real interest in building social events around these communities. We are clearly not in the euphoric era.
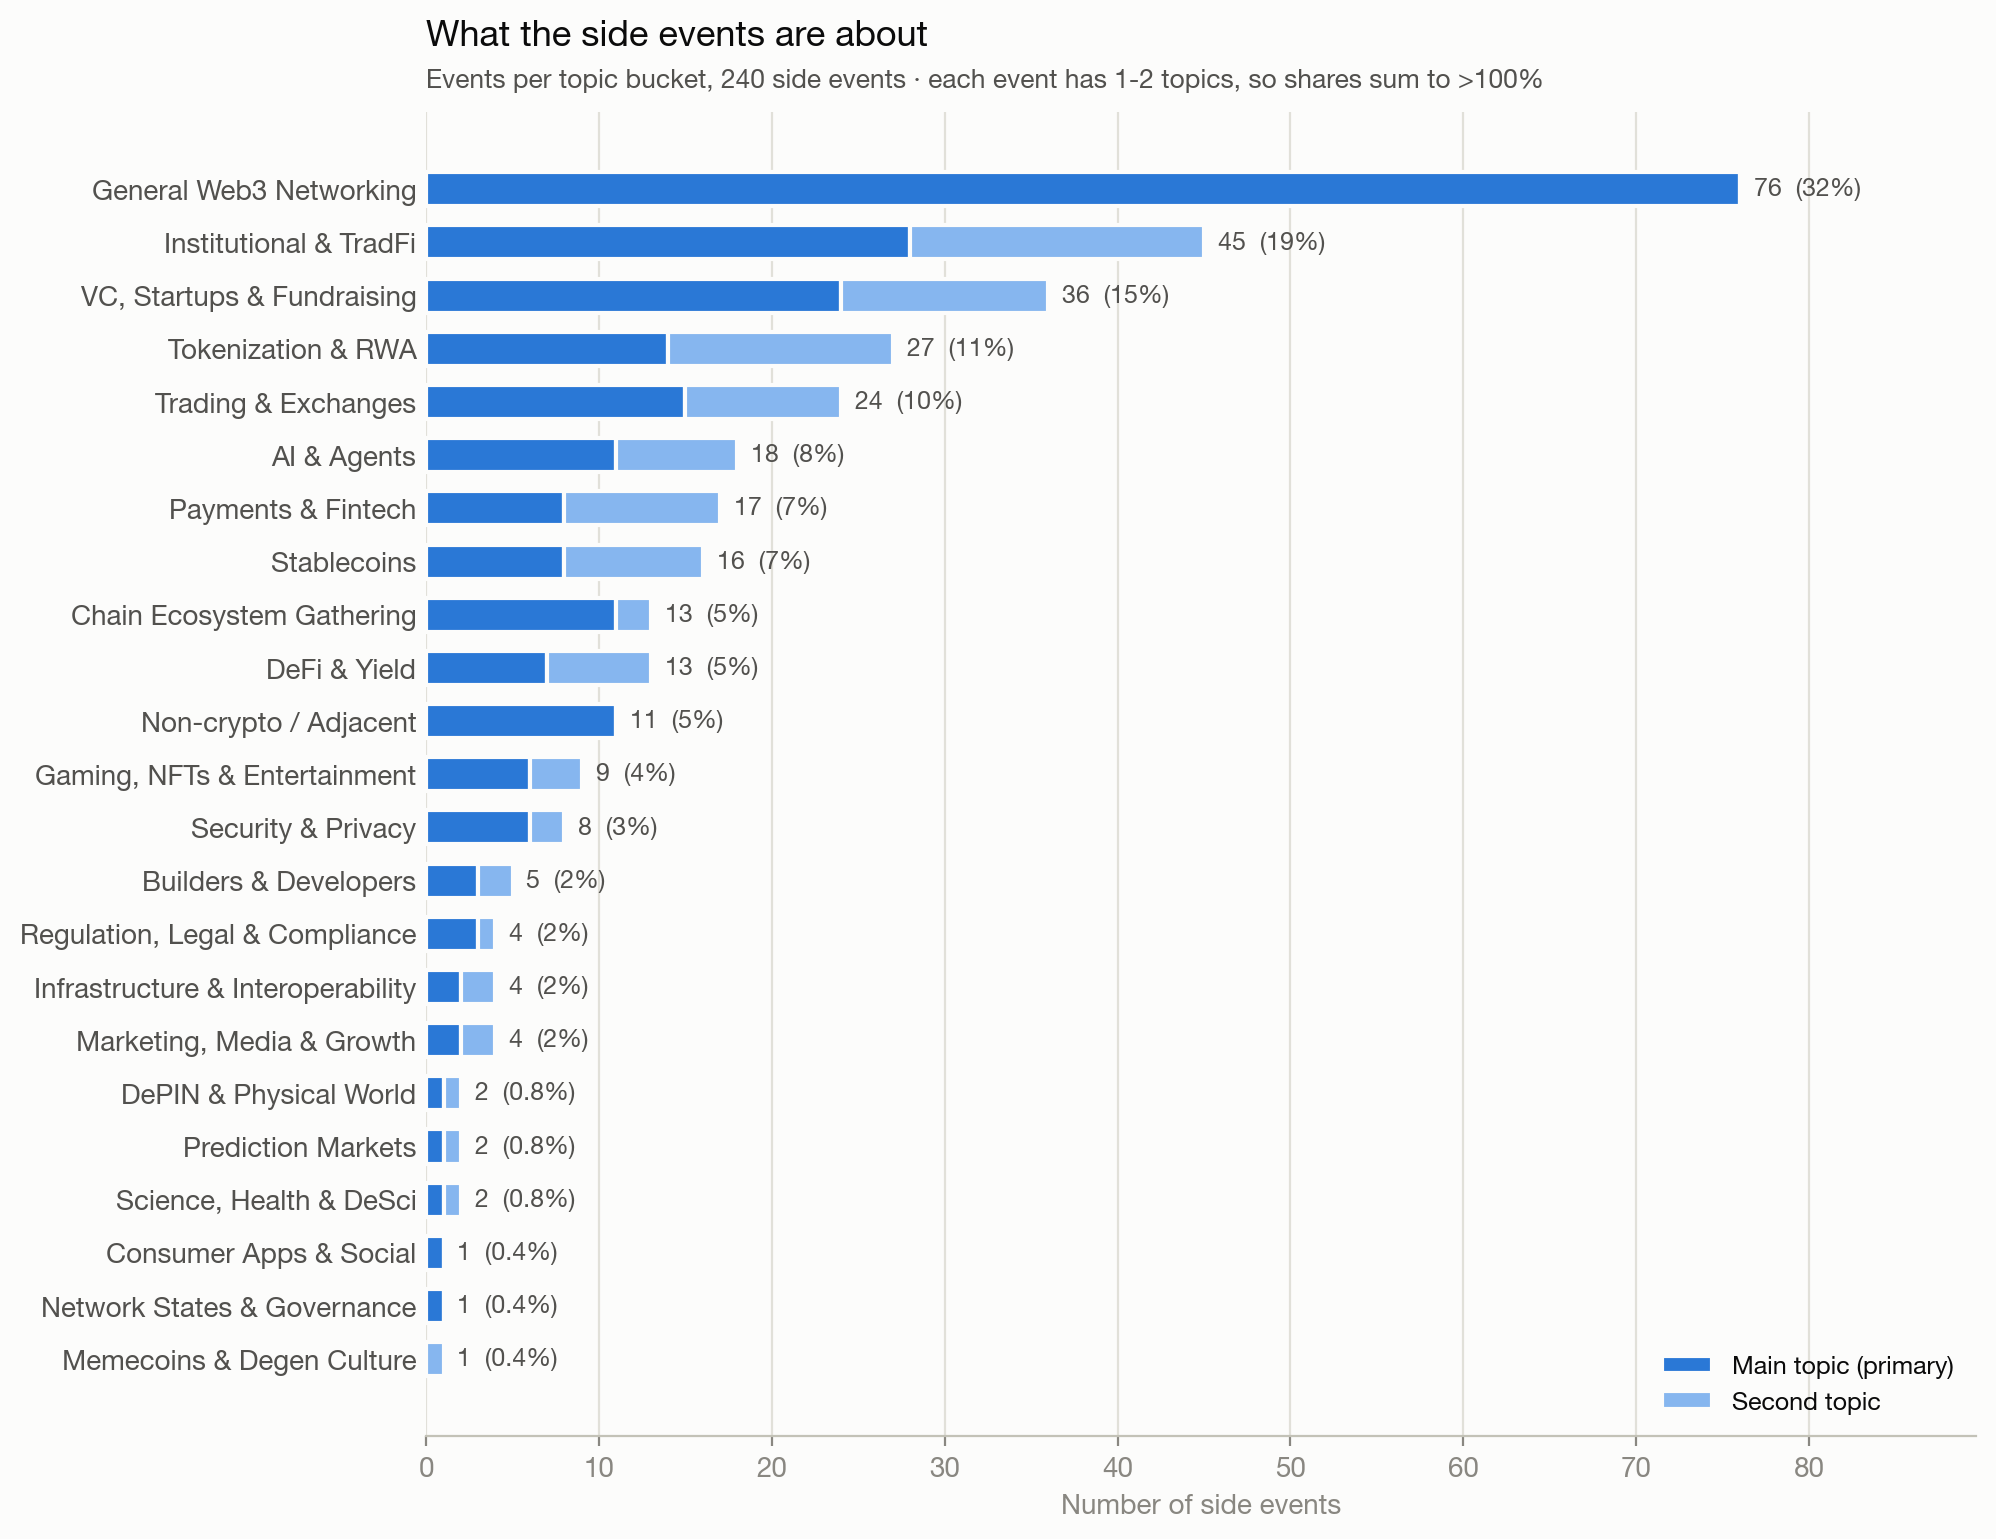
Money and markets, a group that includes tokenization, stablecoins, payments, institutional, DeFi, trading and prediction markets, accounts for 42% of all side events, with over 100 events in this aggregate bucket. This highlights how the industry is evolving toward institutionalization and robust products: the interest is here. The city will be filled with white-shirt boys.
Chain-related events are collapsing: there are only 37 of them. Solana is still winning, with 4 side events related to the chain, and Sui is matching Solana, which is a curious detail.
The share of party and nightlife events this year is strikingly low, so degens and random people are not making money as usual; otherwise, the calendar would be packed. Only 21 events, 9%. We are early.
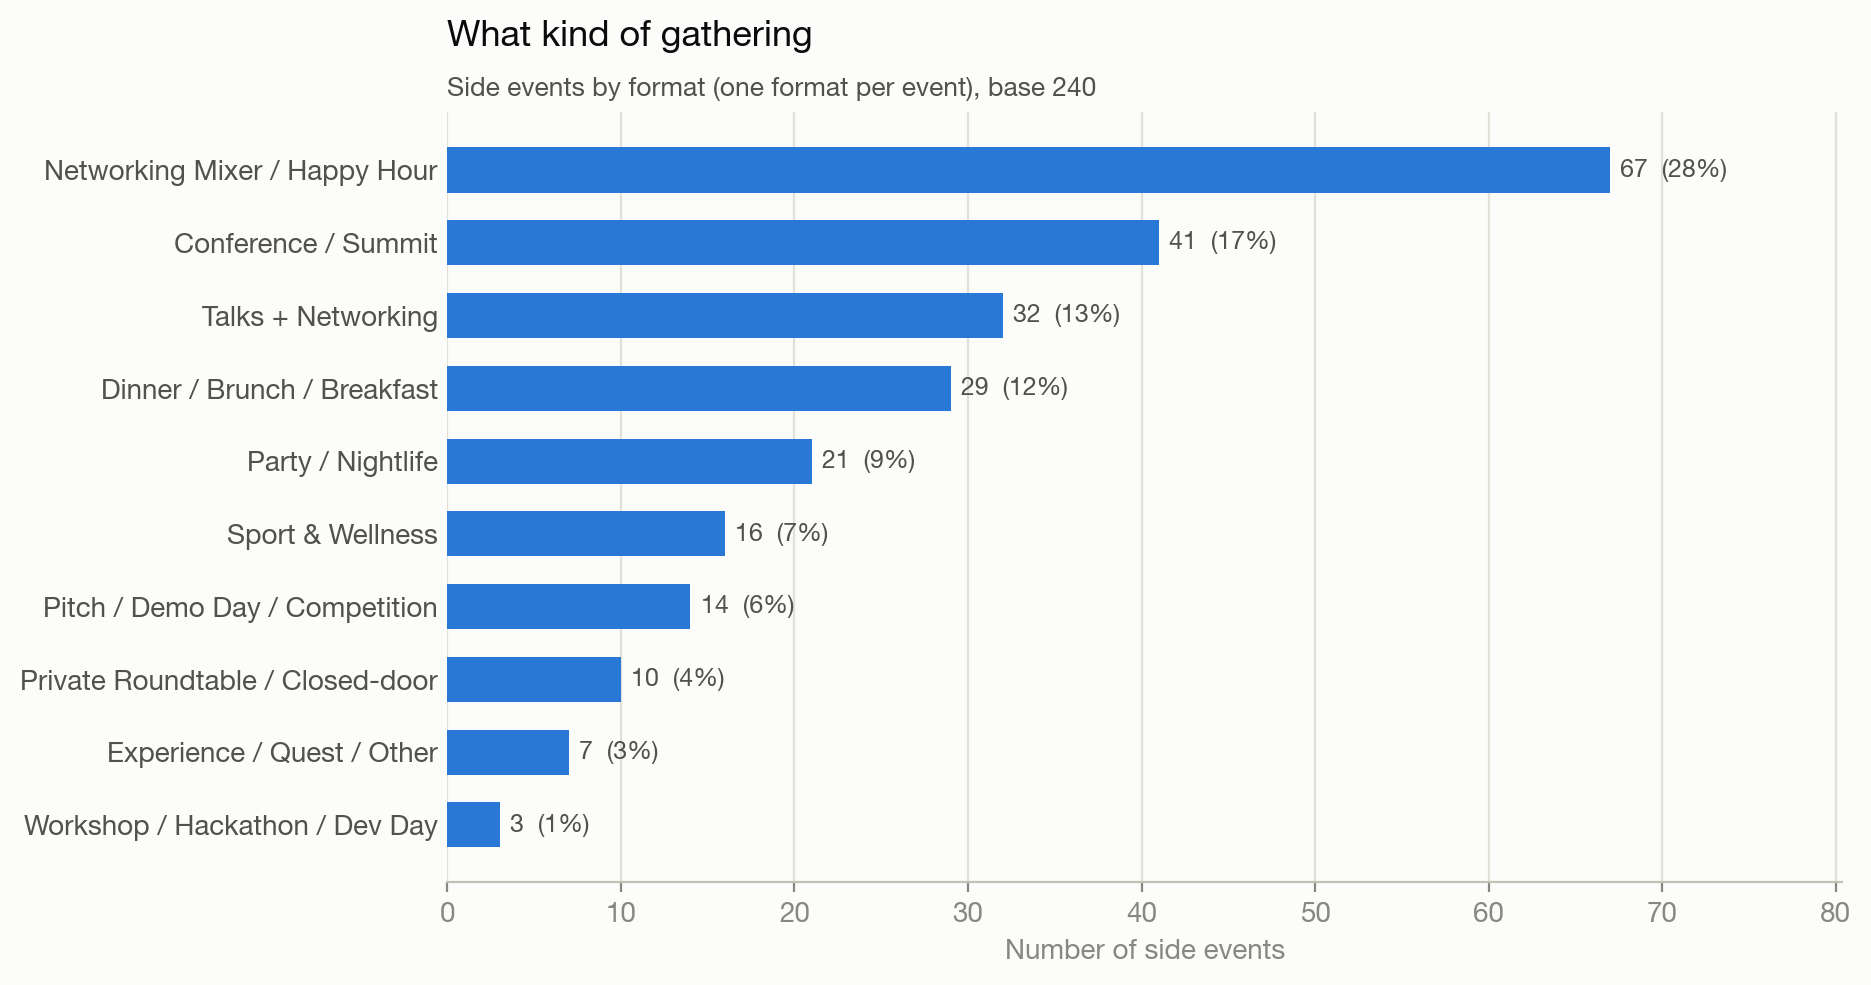
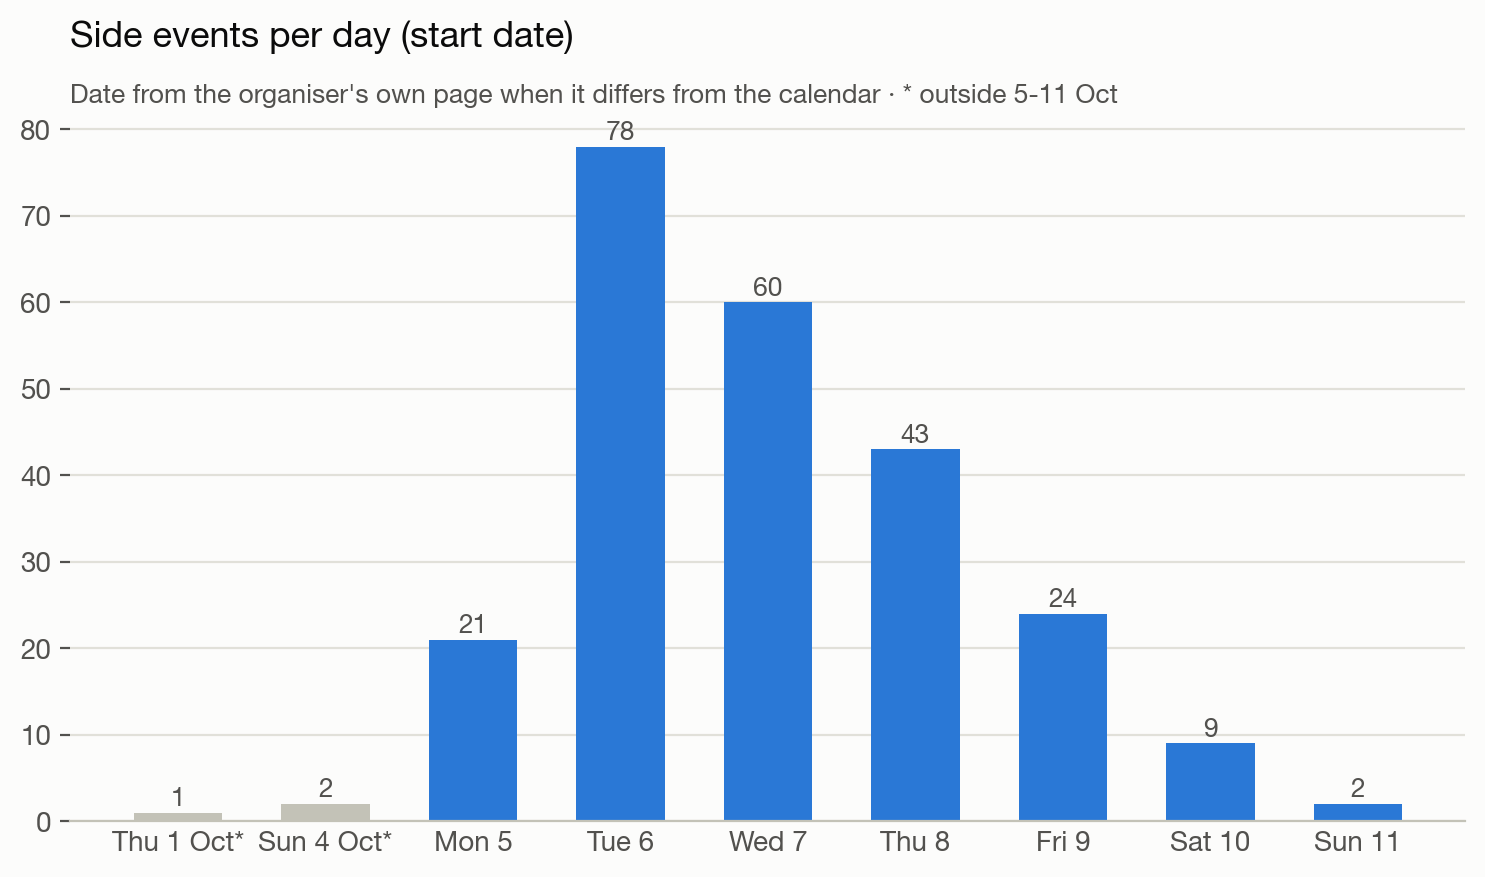
A usual, most side events will happen the day before the main conference, 6 October.
The Takeaway
The market changed, and in changing, it changed who hosts events. Now it is all about institutional adoption, tokenization, exchanges, RWA, stablecoins, TradFi integration and more. This group has been winning share over the last three years, but this year it is truly representative: the events are dominated by this bucket like never before. Wearing a cap and T-shirt will no longer be a valuable look.